When to Calculate Your New Monthly In-Hand Salary
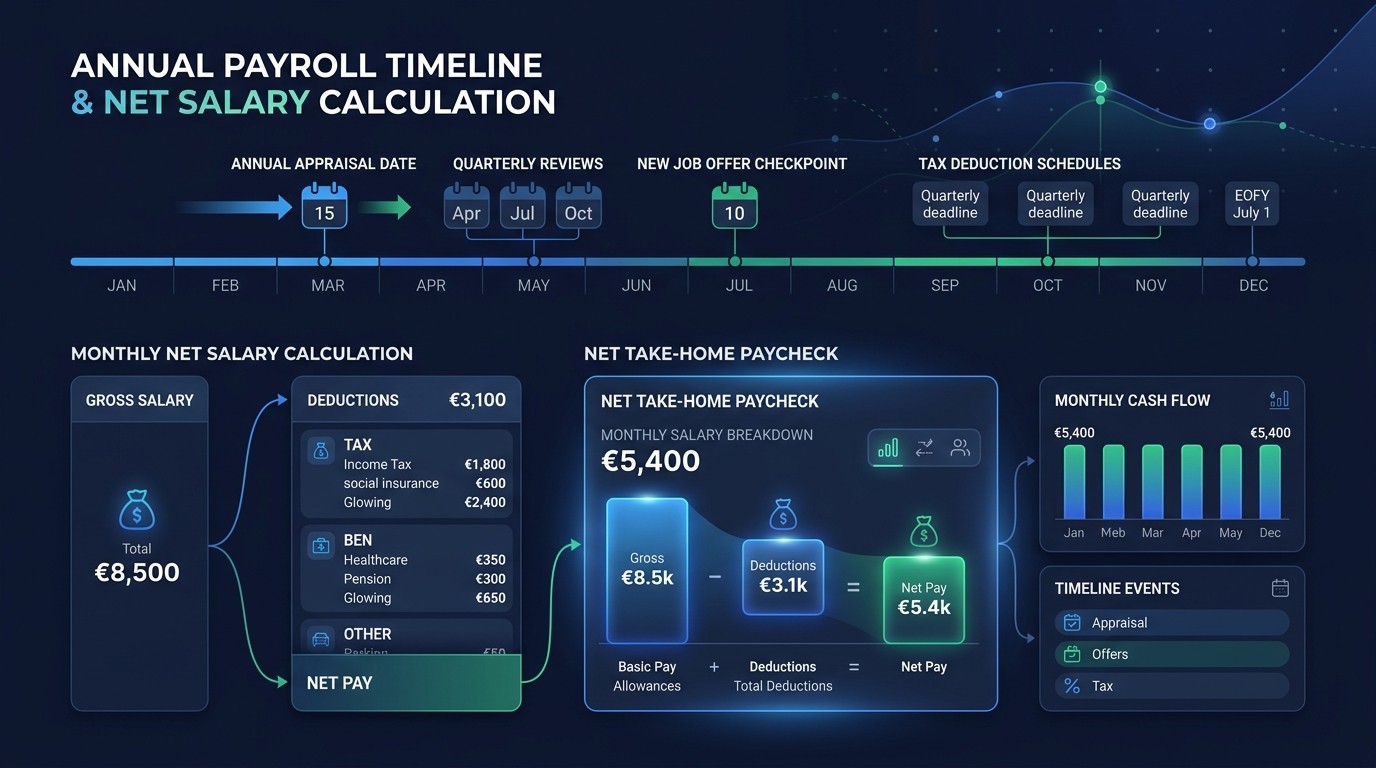
Knowing when to calculate your new monthly in-hand salary helps you plan money before the first paycheck arrives. In-hand salary, also called take-home pay, is what remains after taxes and deductions leave your gross salary. A salary paycheck calculator performs the gross-to-net calculation and shows an estimate in seconds. Running it at the right moments prevents surprises on payday. Several life and work events change your net pay, even when your headline salary stays the same. This guide lists those moments, with a quick reference chart you can reuse.
Why In-Hand Salary Differs From Gross Pay
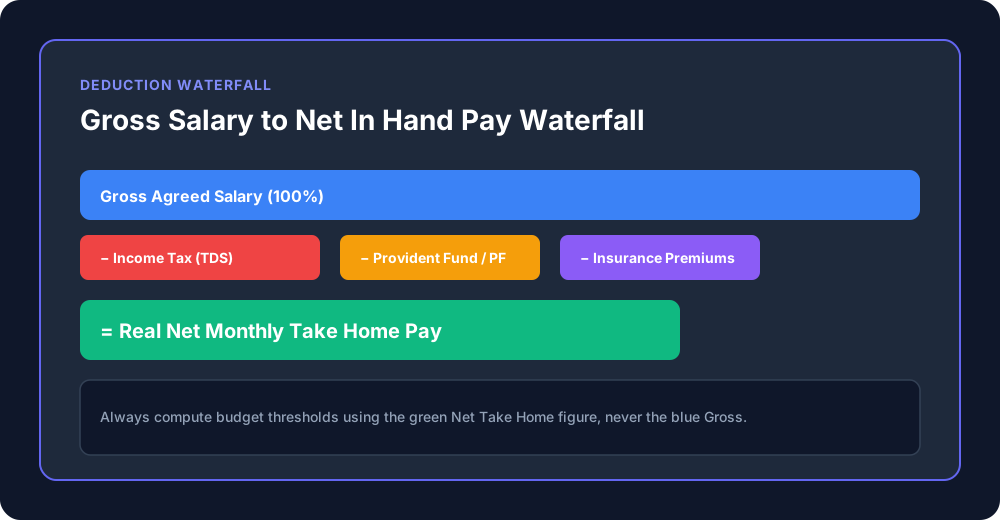
Gross pay is the amount an employer agrees to pay before anything is taken out. Taxes, insurance premiums, retirement contributions, and other deductions reduce it to net pay. That is why a salary offer can look generous yet produce a smaller monthly deposit than expected. Estimating the gross-to-net gap early keeps your budget realistic.
Understanding CTC, Gross Salary, and Net Pay
CTC, or cost to company, is the total an employer spends on you, including benefits that never reach your bank account. Gross salary is the pay amount before deductions, and net pay is the final monthly salary you actually receive. Comparing offers by CTC alone is misleading. Always convert each figure to in-hand salary before deciding which compensation package is better.
When You Receive a New Job Offer
A job offer is the most important moment to calculate take-home pay. Different employers structure salary components, bonuses, and benefits differently, so equal gross salary can still mean unequal net income. If the job is in another state, state taxes may also change the result. Run the calculator before you accept, and ask the employer to clarify unclear deductions.
When an Appraisal or Hike Takes Effect
A salary hike rarely raises net pay by the same percentage as gross pay. Extra income can push earnings into a higher tax bracket, and deductions that scale with pay also rise. Calculate your new monthly salary as soon as the appraisal letter arrives. This shows the real increase in your bank account and helps you negotiate with accurate numbers.
When Switching Between Old and New Tax Regimes
Some countries let employees choose between different tax regimes, each with its own tax rates, exemptions, and deductions. Switching can raise or lower your taxable income and therefore your in-hand salary. In the United States, a change in filing status or withholding works in a similar way. Recalculate net pay under each option before submitting the declaration to your employer.
Key Moments to Recalculate Your Take-Home Pay
| Event | Why Net Pay Changes | What to Check |
|---|---|---|
| New job offer | New structure and deductions | Gross pay, benefits, state |
| Salary hike | Possible higher tax bracket | New gross and deductions |
| Tax regime or filing change | Different rates and exemptions | Withholding choices |
| New financial year | Updated tax rules | Revised tax tables |
| Salary structure change | Components shift | Basic pay and allowances |
| Loan or EMI planning | Fixed monthly outflow | Net pay after deductions |
When a New Financial Year Begins
Tax rules, slab rates, and contribution limits may be updated at the start of a financial year. Your employer may also reset tax withholding based on fresh declarations. Recalculate monthly take-home pay at the start of your tax year, since the same gross salary can produce a different net salary under new rules.
When Your Salary Structure or Components Change
Moving money between basic pay, allowances, bonuses, and benefits alters taxable income even if CTC is unchanged. A larger variable pay share lowers fixed monthly pay, while higher retirement contributions reduce the monthly deposit but build savings. Recalculate whenever HR revises the salary breakup, so the net amount never surprises you.
Before Making Loan, EMI, or Budget Decisions
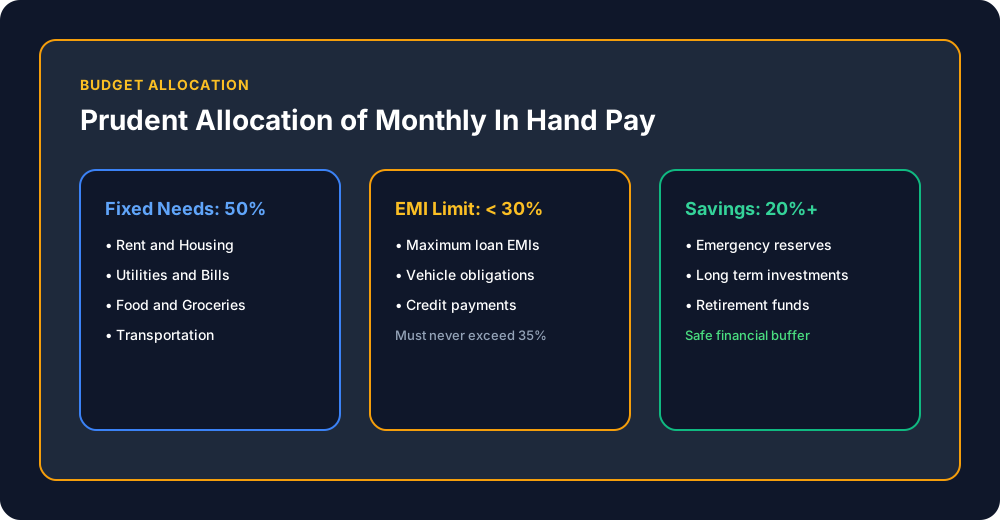
Household budgets depend on net pay, not gross salary. Before taking a loan, committing to an EMI, or signing a lease, calculate your monthly in-hand salary under your current deductions. A fixed obligation should fit comfortably inside take-home pay, leaving room for savings, emergencies, and everyday expenses.
Common Mistakes When Estimating Take-Home Pay
A frequent error is treating CTC as monthly salary. Others include ignoring state taxes, forgetting insurance premiums, and using last year's tax rules. People also overlook bonuses paid annually rather than monthly. Compare the calculator estimate with your first payslip, then investigate any gap, because an estimate is not a final payroll figure.
Quick Reference Chart for Salary Calculation Triggers
The chart above lists the moments when a fresh salary calculation pays off. Use it as a checklist whenever your job, pay, tax status, or budget changes. A gross-to-net calculator takes seconds, while a wrong take-home estimate can disrupt rent, EMI payments, and savings for months. Recalculate early and review each result carefully.
Conclusion
Calculating your new monthly in-hand salary at the right time protects your budget and your decisions. Run a salary paycheck calculator when you accept a job offer, receive a hike, change tax choices, or start a new financial year. Treat every result as an estimate, compare it with your payslip, and confirm details with your payroll team. Accurate monthly take-home pay figures make planning calmer and far more reliable overall.